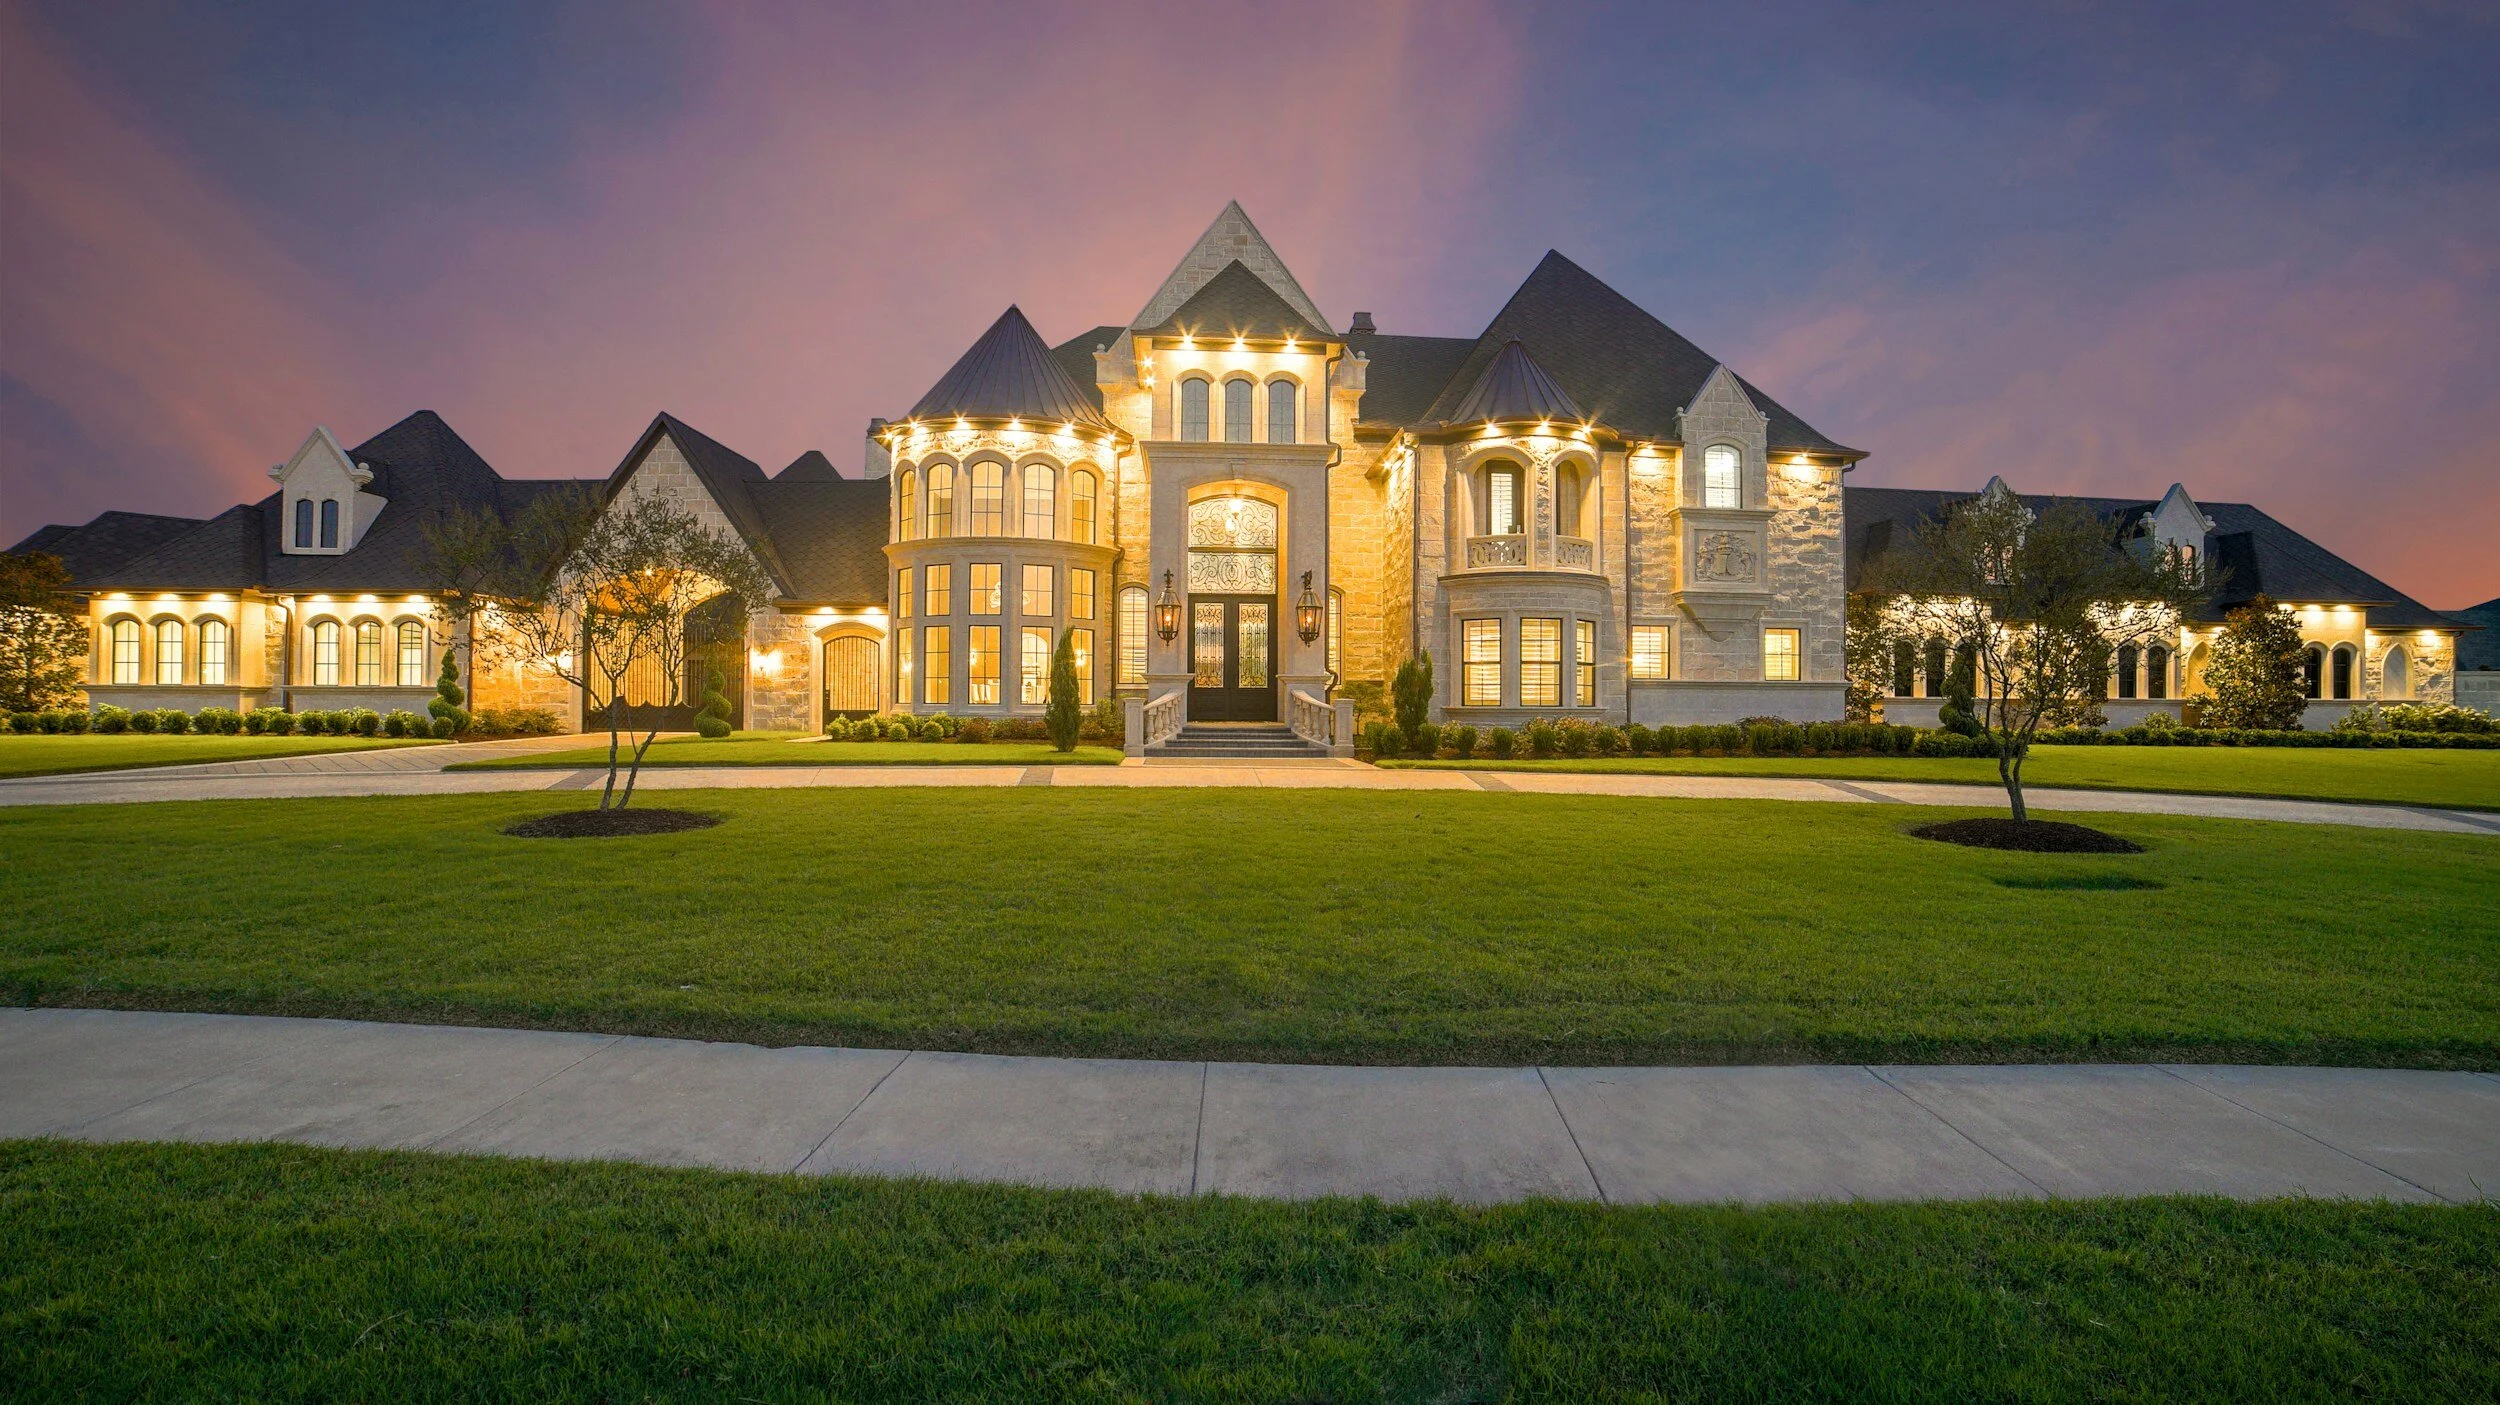
Jumbo Loan
If you're aiming to purchase a luxury home valued well above the standard in your county, a jumbo loan might be the optimal choice for financing your dream property. These loans are specifically designed for homes that exceed the conventional conforming loan limits set by the Federal Housing Finance Agency (FHFA), making them ineligible for traditional financing options.
Jumbo financing is subject to lender review. Loan amounts, documentation and eligibility vary by program and application.
Explore the possibilities of jumbo mortgages today and see if they're the perfect fit for your luxury home purchase aspirations.
What Is a Jumbo Loan?
If you're not familiar with the various mortgage options available, you might be wondering about the definition of a jumbo loan. Essentially, a jumbo loan is a type of home financing that allows borrowers to qualify for a larger loan amount exceeding the conforming loan limits, which typically cap at $726,200 (as of 2/21/23) for most counties. In essence, a jumbo loan, also known as a jumbo mortgage, provides access to higher-end financing beyond what traditional loans can offer.
Typically recommended for individuals looking to purchase homes in competitive real estate markets with higher-than-average prices, jumbo loans enable financing for properties that far exceed typical listing prices. This makes it feasible to purchase such properties, even for financially stable borrowers who may not have the necessary cash on hand for a traditional loan. Jumbo loans facilitate the acquisition of high-value properties by providing financing options tailored to meet these unique needs.
Benefits
For eligible borrowers, securing a jumbo loan offers a range of advantages beyond just the ability to afford a luxury home.
Loan amounts and terms: Request a current Loan Estimate to compare available options. Pricing and down payment requirements depend on the lender and your application.
Faster Processing: Another significant benefit of obtaining a jumbo loan through Fyzl Group Ltd is the expedited processing time compared to traditional banks. Currently, banks are taking anywhere from 60 to 120 days to process these loans. However, in many cases, we can complete the loan process within 30 days or less, ensuring a quicker turnaround for our borrowers.
If you have further inquiries about how jumbo loans operate or wish to determine your eligibility, don't hesitate to speak with one of our knowledgeable loan officers today.
Jumbo Loan Interest Rates
What are jumbo loan rates? Typically, the average interest rate for a jumbo loan resembles that of a traditional loan. However, your interest rate may also be influenced by various factors such as your debt-to-income ratio, down payment amount, and other relevant considerations.
In today’s market, most jumbo loans are offered as either 30-year or 15-year fixed-rate mortgages. An adjustable-rate mortgage (ARM) is another option, where the interest rate remains fixed for a specified period (often five or seven years), after which it may adjust based on prevailing market conditions. Conversely, a fixed-rate mortgage entails a consistent interest rate throughout the loan term, whether it spans 15 or 30 years.
Requirements and Qualifications
As previously mentioned, jumbo loans generally impose more stringent requirements due to the larger loan amounts involved. Here are some of the key jumbo loan requirements and qualifications to consider:
Credit Score: Jumbo mortgages are intended for borrowers who demonstrate strong financial stability. Consequently, a higher credit score is typically required, often in the range of 700 or above. This ensures that borrowers can effectively manage the substantial loan amount. For instance, while a traditional FHA loan may accept credit scores as low as 580, an FHA jumbo loan demands a higher credit score among other criteria.
Debt-to-Income Ratio (DTI): Your debt-to-income ratio (DTI) reflects the proportion of your income allocated towards debt payments. Lower DTI ratios are generally preferred. While some traditional home loans may permit DTI ratios of up to 55%, jumbo loan applicants typically need to maintain a significantly lower DTI ratio, often below 43% or even 36%.
Cash Reserves: To qualify for a jumbo mortgage, lenders typically require substantial savings or liquid assets that can readily cover several months or even a year's worth of mortgage payments. This demonstrates financial stability and mitigates the lender's risk.
Documentation of financial health: Ask your selected lender which income, asset and reserve documentation your application requires.
Property Appraisal: Before final loan approval, a property appraisal is usually required to ascertain the property's value and structural integrity. Jumbo loans may necessitate additional appraisals, particularly for luxury properties, to ensure accuracy.
Down payment: Requirements vary by lender, program, property and application. Confirm the current requirements before planning your financing.
Join Our Mailing List
Real estate and financial services
FYZL GROUP
Agents & Lenders
Honesty | Integrity | Diligence